NAICOM Tasks Insurers On Governance After Successful Recapitalisation
BY NGOZI ONYEAKUSI
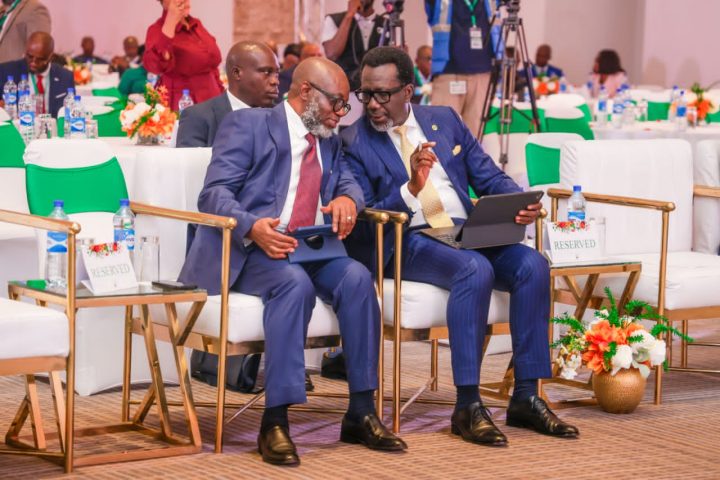
The National Insurance Commission (NAICOM) has urged insurance companies to strengthen corporate governance, risk management and board oversight, warning that successful recapitalisation alone does not guarantee institutional resilience.
The Commissioner for Insurance and Chief Executive of NAICOM, Mr Olusegun Ayo Omosehin, gave the charge at the 8th Annual Insurance Directors’ Conference held on Thursday, November 5, 2026, at the Marriott Hotel, Ikeja, Lagos.
The conference, organised by the College of Insurance and Financial Management in collaboration with NAICOM, had the theme, “Recapitalisation to Resilience: Leading the Risk-Based Capital (RBC) Era.”
Omosehin, who described the conclusion of the recapitalisation exercise as the beginning of a more demanding phase for the industry, said insurers must now demonstrate their ability to translate stronger capital positions into improved underwriting capacity, effective risk management, better claims-paying ability and sustainable growth.
He stressed that the strength of an insurance institution should not be measured by its capital base alone but also by the quality of its leadership, internal controls, board oversight and the discipline with which it conducts its business.
According to him, institutions with substantial financial resources can still fail because of poor governance, weak internal controls, ineffective risk management, inappropriate investments and inadequate board supervision.
He therefore called for a more active role for company directors, urging them to move beyond merely receiving management reports to asking critical questions,
challenging management assumptions and ensuring that strategic decisions are backed by reliable information.
The NAICOM chief identified strategic leadership, capital stewardship, effective risk governance, management accountability, internal controls and board effectiveness as key responsibilities directors must strengthen in the post-recapitalisation era.
He warned that capital could be eroded through poor underwriting, excessive operating costs, inappropriate investments and uncontrolled business expansion if boards failed to exercise proper oversight.
“Capital management must be a continuous board responsibility and not merely a matter for the finance department or an occasional regulatory review,” he said.
Omosehin also cautioned that the legitimate expectations of shareholders for returns and business growth must not override prudential considerations, undermine board independence or encourage unsustainable business strategies.
On the transition to Risk-Based Capital, he explained that while the Minimum Capital Requirement establishes the minimum capital threshold an insurance institution must maintain to operate, the Risk-Based Capital framework goes further by assessing the risks assumed by an institution and the capital required to support them.
He noted that an insurance company could meet the minimum capital requirement and still have insufficient capital to support the nature, scale and complexity of its risk exposures.
Consequently, he said NAICOM’s supervisory approach would increasingly focus on capital quality, risk management frameworks, governance effectiveness, institutional resilience and insurers’ ability to meet their obligations to policyholders.
He added that the Commission would place greater emphasis on the accuracy, completeness and timeliness of regulatory returns, financial reports, actuarial assessments and disclosures.
“Successful recapitalisation does not confer permanent immunity from regulatory scrutiny. Capital adequacy is a continuous responsibility,” he warned.
Beyond strengthening individual companies, Omosehin said the recapitalisation exercise offered an opportunity to reposition the insurance industry as a stronger contributor to Nigeria’s economic development.
He identified infrastructure, energy, manufacturing, agriculture and construction as sectors requiring a dependable insurance industry capable of supporting investments and managing increasingly complex risks.
He also said stronger insurance institutions could deepen domestic risk-retention capacity, reduce dependence on foreign insurance markets, provide long-term institutional investment and expand access to affordable insurance products.
However, he maintained that these benefits would only materialise if insurers improved service delivery, developed innovative products and strengthened public confidence through prompt and fair claims settlement.
On policyholder protection, the Commissioner emphasised that the public measures the strength of insurance companies by their willingness and ability to honour contractual obligations, rather than the size of their capital alone.
He urged boards to make policyholder protection central to their corporate strategies, describing claims settlement as one of the most important determinants of public confidence in the industry.
He further stressed the importance of the Fit and Proper Framework, saying appointments to boards and senior management positions must be based on competence, character, experience and professional integrity rather than status, familiarity or influence.
Omosehin maintained that directors must recognise the increased responsibilities that come with the industry’s transition into the post-recapitalisation era.
He described them as custodians of policyholders’ trust, stewards of shareholders’ investments and guardians of institutional integrity, adding that decisions taken in boardrooms would determine whether the gains of recapitalisation were sustained.
He urged insurance companies to ensure that the current reform period was remembered not merely as a time when operators raised additional capital, but as a turning point for improved governance, stronger institutions and greater relevance to Nigeria’s economic development.

Leave a Reply