FirstBank’s ₦6bn Cybersecurity Investment Aligns with IMF Fraud Warning
BY NGOZI ONYEAKUSI

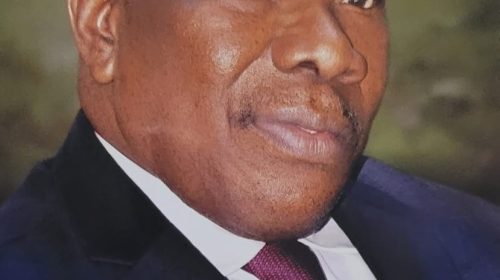
MD/CEO FirstBank
The growing need to protect investments and strengthen safeguards against digital financial crime took centre stage at the just-concluded 2026 International Monetary Fund (IMF) and World Bank Annual Meetings in Bangkok, Thailand, where speakers raised concerns over cyber attacks, the potential risks associated with artificial intelligence (AI), and other emerging threats to financial security.
Against this backdrop, FirstBank Nigeria’s annual investment of more than ₦6 billion in cybersecurity has gained renewed relevance as global financial institutions intensify calls for stronger measures to combat fraud and protect digital financial services.
During the meetings, the IMF and World Bank, in partnership with the Bank of Thailand, unveiled the Bangkok Blueprint for Fraud-Resilient Financial Services, a framework designed to strengthen the prevention, detection and response to cyber-enabled fraud.
The initiative reflects growing concerns that while technological innovations are expanding access to financial services and improving transaction efficiency, they are also creating new opportunities for fraudsters to exploit digital platforms and target customers.
FirstBank’s investment in cybersecurity underscores the importance of strengthening the protection of banking infrastructure, safeguarding customers’ funds and preserving public confidence in digital transactions.
The bank’s Chief Executive Officer, Olusegun Alebiosu, recently disclosed that FirstBank spends more than ₦6 billion annually on cybersecurity to protect its systems against cybercriminals.
He also revealed that the bank operates round-the-clock surveillance of its systems and has established a command centre to monitor operations and respond to emerging threats.
The investment comes at a time when financial institutions face increasing pressure to keep pace with evolving cyber threats, particularly as digital banking becomes more widespread and criminals deploy increasingly sophisticated methods to perpetrate fraud.
The concerns highlighted at the Bangkok meetings also point to the need for a broader approach to financial security, extending beyond technology investments to include effective regulation, institutional cooperation and greater awareness among customers and employees.
For Nigerian banks, protecting digital transactions requires continuous monitoring of banking systems, the identification of suspicious activities, the protection of sensitive information and prompt responses to potential security breaches.
The Bangkok Blueprint promotes coordinated action among financial institutions, regulators, policymakers and other stakeholders, recognising that cyber-enabled fraud can cross national borders and undermine confidence in the wider financial system.
As artificial intelligence continues to reshape financial services, banks must also strengthen their capacity to identify and respond to emerging risks associated with the technology, while ensuring that innovation does not compromise the security of customers and their investments.
FirstBank’s cybersecurity spending therefore aligns with the broader international push for more resilient digital financial services, highlighting the growing importance of security as banks expand their technology-driven operations.
For the Nigerian banking sector, sustained investment in cybersecurity and stronger collaboration among industry stakeholders will be critical to protecting customers, reinforcing trust in digital transactions and supporting financial stability as technology continues to transform the industry.

Leave a Reply